Net Worth
Do you know what you are actually worth today? Or are you going off a number you calculated in your head two years ago?
Most people track the balance, not the picture
You know what is in checking. You probably know roughly what the 401(k) said last time you looked. But the mortgage, the car, the student loans and the card you have been chipping at all live in separate places, and nobody adds them up on the same page.
So the number you carry around in your head is usually the number from the one account you check most, and it is almost never the truth.
Net worth is the only figure that accounts for everything at once. Everything you own, minus everything you owe. It is the scoreboard, and most households have never actually looked at it.
Everything you own, minus everything you owe
Tap any candle and it opens up. Every account on the left, every balance you owe on the right, and the subtraction at the bottom. That is the whole arithmetic, and it is the same arithmetic on the day you started as on the day you retire.
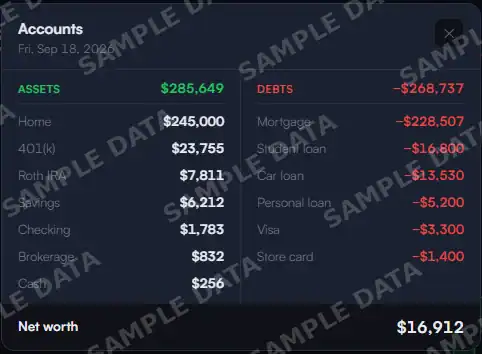
Sample data. The demo household, shown to illustrate how the tool works.
What comes out of it
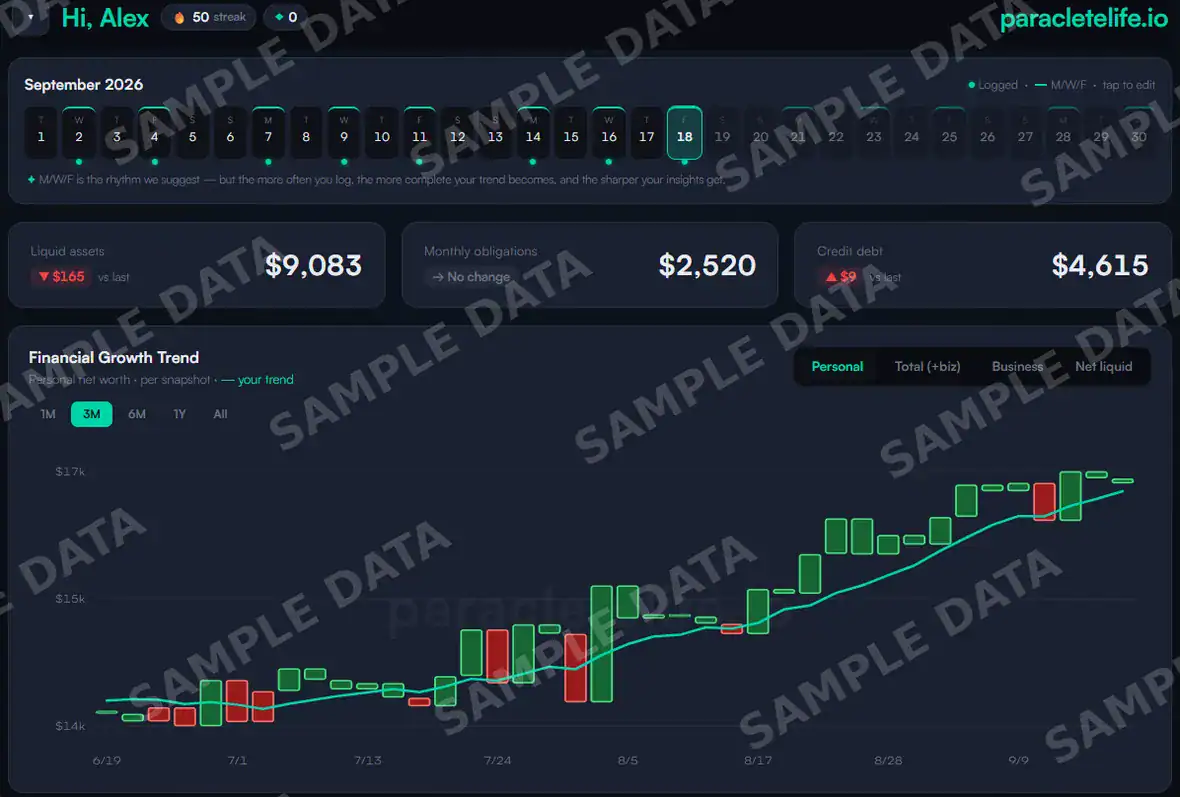
Sample data. The demo household, shown to illustrate how the tool works.
Every time you log, it drops a candle. Green when the period closed above where it opened, red when it did not, and the line running through them is your trend.
You can pull it back to a month, a quarter, a year or the whole history, and you can split it four ways. Personal, personal plus the business, the business on its own, or net liquid only. Same entries, four different questions.
Liquid assets, monthly obligations and credit debt sit across the top with the change since your last entry, so you can see which one moved the number.
The number matters less than which way it is moving
Two households can sit at the same figure and be in completely different situations. One is paying down a mortgage and adding to retirement every month. The other is borrowing to hold steady. The snapshot cannot tell them apart. The direction can.
So the point of running this more than once is the slope. Where it was, where it is, and whether the things you have been doing all year actually moved it.
What it needs from you
01
Balances, not estimates
Pull the real numbers. A guess on the mortgage payoff will throw the whole thing off by more than you expect.
02
Every account, including the ones you forgot
The old 401(k) from two jobs ago counts. So does the card with the small balance you never think about.
03
An honest value on the house and the cars
Not what you paid and not what you hope. What it would sell for this month.
04
The habit of coming back
Once is a number. The trend only exists because you kept logging, so the second entry matters more than the first one did.
Where this sits in the bigger picture
This is the starting line, because every plan needs to know where it is starting from.
Skip it and every goal you set is measured against a number nobody checked.
Questions people ask
What if my net worth is negative?
Then you found out, which is the whole point. Most households carry a mortgage and student loans for years before the line crosses zero. Negative and improving is a position you can work with.
Do I include my house?
Yes, on both sides. The market value goes in what you own and the mortgage balance goes in what you owe. Leaving either one out gives you a number that means nothing.
How often should I log it?
Monday, Wednesday, Friday is the rhythm the tool suggests, and it tracks your streak. The more often you log, the more complete the trend gets and the sharper it reads.
Do I have to connect my accounts?
No. There is no bank or brokerage login anywhere in this. You enter the numbers.
Is it really free?
Thirty days of everything, no card, using the code at signup. After that there is a free tier that keeps working, and paid tiers if you want the rest.
Is this financial advice?
No. It adds and subtracts the figures you give it. What that result means for your situation is a conversation, not a calculation.